
A lot of people put off investing because they think they need thousands of dollars to begin. That used to be partly true. Today, it isn’t.
Most major brokerages now offer $0 commissions on stock and ETF trades, many have no account minimums, and fractional shares let you buy a slice of a stock for as little as a few dollars. That means you can start investing with $50 or even less.
This guide walks you through exactly how to start investing with little money, step by step, and how small amounts can grow into something meaningful over time.
Table of Contents
Why Starting Small Still Matters
When you’re investing $50 a month, it can feel pointless. But the biggest advantage you have isn’t the size of your deposits. It’s time.
Investing works through compounding. Your money earns returns, and then those returns earn returns of their own. The longer your money stays invested, the more powerful this becomes.
Here’s what investing a small amount each month could grow to, assuming a hypothetical 7% average annual return:
| Monthly investment | After 10 years | After 20 years | After 30 years |
|---|---|---|---|
| $50 | $8,654 | $26,046 | $60,999 |
| $100 | $17,308 | $52,093 | $121,997 |
At $100 a month for 30 years, you’d contribute $36,000 of your own money. Compounding does the rest. You can try your own numbers with the SEC’s free compound interest calculator.
This is a hypothetical example for illustration only. Investment returns are not guaranteed, and the value of investments can go down as well as up.
Learning how to start investing with little money is really about building a habit. The amount you invest in the first year matters less than getting your accounts set up, choosing simple investments and making regular contributions part of your routine. Once the habit is in place, it is much easier to invest more as your income grows.
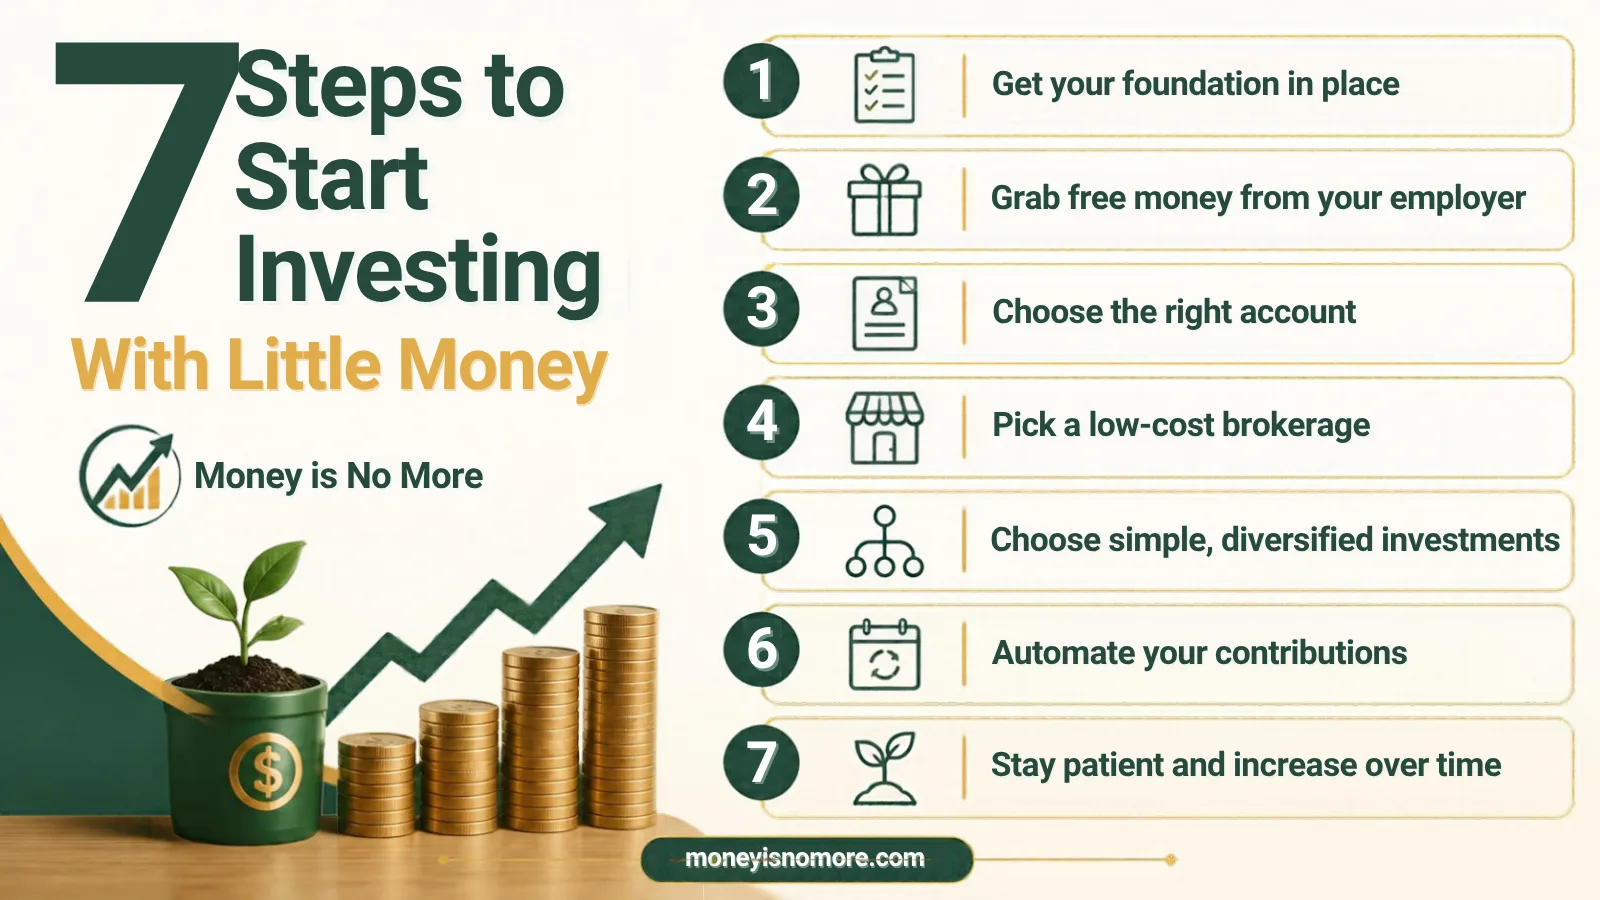
Step 1: Get Your Foundation in Place
Before you invest a single dollar, make sure two things are handled.
Pay off high-interest debt. Credit cards often charge more than 20% interest. No investment reliably beats that, so paying down card debt is effectively a guaranteed return. Our guide to the debt snowball vs. avalanche can help you choose a payoff plan.
Build a small emergency fund. Investments go up and down. If an emergency forces you to sell during a downturn, you could lock in a loss. Even $1,000 in a savings account gives you a buffer. If saving is tough, the 52-week savings challenge is an easy way to start.
Step 2: Grab Any Free Money From Your Employer
If your employer offers a 401(k) or similar plan with a match, start there. A common match is something like 50% or 100% of what you contribute, up to a certain percentage of your pay.
That match is essentially free money. If your company matches dollar for dollar up to 4% and you contribute 4%, you’re instantly doubling that portion of your investment. Few other opportunities come close.
Even if you can only contribute a small percentage, try to contribute at least enough to get the full match.
Step 3: Choose the Right Account
If you don’t have a workplace plan, or you want to invest beyond it, you’ll need to open your own account. The most common options for beginners are:
Roth IRA
A Roth IRA lets you invest money you’ve already paid taxes on. Your investments then grow tax-free, and qualified withdrawals in retirement are tax-free too. For 2026, the IRS allows you to contribute up to $7,500 a year (or $8,600 if you’re 50 or older), subject to income limits.
A Roth IRA is often a great choice for beginners, especially if you’re early in your career and in a lower tax bracket.
Traditional IRA
A traditional IRA may give you a tax deduction now, but you’ll pay taxes when you withdraw the money in retirement. The contribution limits are the same as a Roth IRA.
Taxable brokerage account
A regular brokerage account has no contribution limits and no restrictions on when you can withdraw. The trade-off is that you’ll pay taxes on dividends and gains. It’s a good option for goals that are more than five years away but aren’t retirement.
Step 4: Pick a Low-Cost Brokerage
Look for a brokerage that offers:
- No account minimum, so you can start with any amount.
- $0 commissions on stock and ETF trades.
- Fractional shares, so you can invest a set dollar amount instead of buying whole shares.
- Automatic investing, so you can set up recurring contributions.
- SIPC protection, which protects customer assets if a brokerage firm fails (it does not protect against market losses).
Most large, well-known brokerages check every box. Compare a few and choose the one with an app and website you find easy to use.
Step 5: Choose Simple, Diversified Investments
When you’re starting with a small amount, simple is best. Picking individual stocks is risky because your money depends on just a few companies.
Instead, most beginners are better off with:
- Broad-market index funds or ETFs. These hold hundreds or thousands of companies in one fund. An S&P 500 or total stock market fund is a common starting point. Learn more in our guide to index funds for beginners.
- Target-date funds. These automatically adjust your mix of stocks and bonds as you get closer to a chosen retirement year. They’re a true “set it and forget it” option.
Pay close attention to fees. A fund’s expense ratio is the yearly fee you pay as a percentage of your investment. Small differences add up over decades, so favor funds with low expense ratios.
Step 6: Automate Your Contributions
The most reliable way to invest consistently is to make it automatic. Set up a recurring transfer from your checking account to your investment account on payday.
This also helps you use dollar-cost averaging. By investing the same amount on a regular schedule, you buy more shares when prices are low and fewer when they’re high. It takes emotion out of the process and stops you from trying to time the market.
Need to find room in your budget? The 50/30/20 rule sets aside 20% of your income for savings and investing.
Step 7: Stay Patient and Increase Over Time
Markets will have bad years. That’s normal. The worst thing a beginner can do is panic and sell when prices drop.
Keep investing through ups and downs, and look for chances to increase your contributions:
- Raise your contribution by 1% each year.
- Invest part of every raise or bonus.
- Put extra income from a side hustle straight into your investment account.
If you’d like to build income beyond your paycheck, our list of passive income ideas for beginners is a good place to explore.
Quick Recap: How to Start Investing With Little Money
Build a small emergency fund and pay down high-interest debt first. Grab any employer match, open the account that fits your goals, and choose a low-cost brokerage. Keep your investments simple and diversified, automate your contributions, and increase them a little whenever you can. That is how to start investing with little money and stay with it for the long run.
Common Mistakes to Avoid
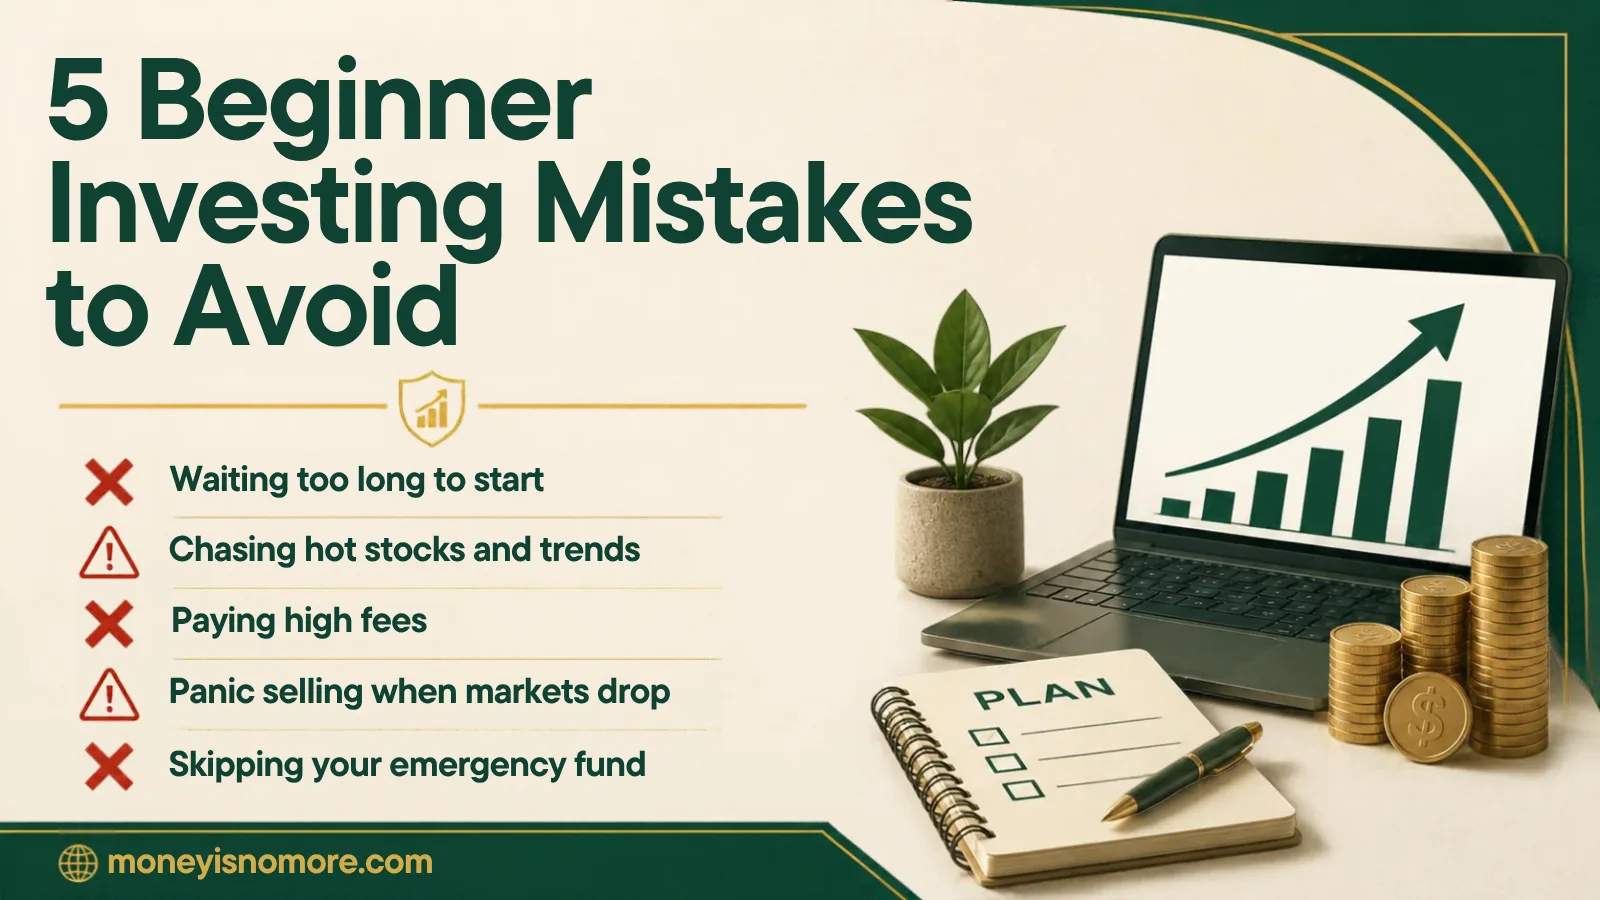
- Waiting until you have “enough.” Time in the market matters more than starting amount.
- Chasing hot stocks or crypto tips. High-risk bets can wipe out small portfolios quickly.
- Ignoring fees. High fees quietly eat into your returns year after year.
- Checking your balance constantly. Daily swings can tempt you into bad decisions.
- Investing money you’ll need soon. Money for the next few years belongs in savings, not the stock market.
Frequently Asked Questions
Can I start investing with $100?
Yes. With fractional shares and no-minimum brokerage accounts, you can start investing with $100 or less. Many beginners put that money into a broad index fund or ETF.
What is the best investment for beginners with little money?
Low-cost, broad-market index funds or ETFs are a popular choice because they offer instant diversification with low fees. Target-date funds are another simple option.
Is it better to save or invest?
Save first for emergencies and short-term goals. Invest money you won’t need for at least five years, since investments can drop in value in the short term.
How much should I invest each month as a beginner?
Start with whatever you can afford consistently, even $25 or $50. Many experts suggest working up to 15% of your income for retirement over time.
Is investing risky?
All investing carries risk, including the possible loss of money. Diversifying, keeping fees low, and investing for the long term can help manage that risk.
This article is for educational purposes only and is not personalized investment advice.

Leave a comment