
If you’re looking into index funds for beginners, there’s a good chance someone has already told you to “just buy an index fund.” It’s some of the most common advice in personal finance, and for good reason.
Index funds are simple, low-cost, and instantly diversified. You don’t need to research individual companies or watch the market every day. You buy one fund and own a small piece of hundreds or even thousands of businesses.
This guide to index funds for beginners explains what index funds are, why so many investors use them, the different types to know, and exactly how to buy your first one in four simple steps.
Table of Contents
What Is an Index Fund?
An index fund is a type of mutual fund or exchange-traded fund (ETF) that aims to match the performance of a market index.
A market index is simply a list of investments that represents part of the market. Some well-known examples:
- S&P 500: about 500 of the largest U.S. companies.
- Total U.S. stock market: nearly every publicly traded U.S. company.
- Total international stock market: companies outside the U.S.
- U.S. aggregate bond index: a broad mix of U.S. investment-grade bonds.
An S&P 500 index fund, for example, buys the stocks in the S&P 500 so its returns closely follow that index. The fund doesn’t try to beat the market. It tries to be the market.
According to the SEC’s investor bulletin on index funds, this passive approach usually means lower management costs, because the fund isn’t constantly buying and selling to chase returns.
Why Index Funds for Beginners Make So Much Sense
1. Instant diversification
When you buy a single stock, your money depends on one company. When you buy a total market index fund, it’s spread across thousands. If one company struggles, it barely affects your overall investment.
2. Very low fees
Fees matter more than most beginners realize. According to the Investment Company Institute’s 2025 fee study, the average asset-weighted expense ratio for index equity mutual funds was just 0.05%, compared with 0.64% for actively managed equity mutual funds.
That gap adds up. Suppose you invest $10,000 for 30 years and earn a hypothetical 7% a year before fees:
- With a 0.05% fee, you’d end up with about $75,063.
- With a 0.64% fee, you’d end up with about $63,584.
That’s roughly $11,500 lost to fees on a single $10,000 investment.
Hypothetical example for illustration only. Actual returns will vary.
3. Strong long-term track record
It’s hard for professional fund managers to consistently beat the market. S&P Dow Jones Indices tracks this in its SPIVA scorecard. In 2025, 79% of actively managed U.S. large-cap funds underperformed the S&P 500.
When most active managers trail the index, simply owning the index is a strong strategy.
4. Simple and hands-off
You don’t need to analyze earnings reports or decide when to buy and sell. That simplicity makes it easier to stay invested, which is one of the biggest keys to long-term success.
Index Mutual Funds vs. Index ETFs
Index funds come in two main forms. Both can track the same index, but they work a little differently.
| Feature | Index mutual fund | Index ETF |
|---|---|---|
| How it trades | Once a day, at the closing price | Throughout the day, like a stock |
| Minimum investment | Some funds require a minimum | Price of one share, or less with fractional shares |
| Automatic investing | Usually easy to set up | Depends on your brokerage |
| Typical costs | Low for index funds | Low for index ETFs |
When it comes to index funds for beginners, either form works well. If your brokerage lets you automatically invest a set dollar amount, choose whichever makes that easiest.
Types of Index Funds to Know
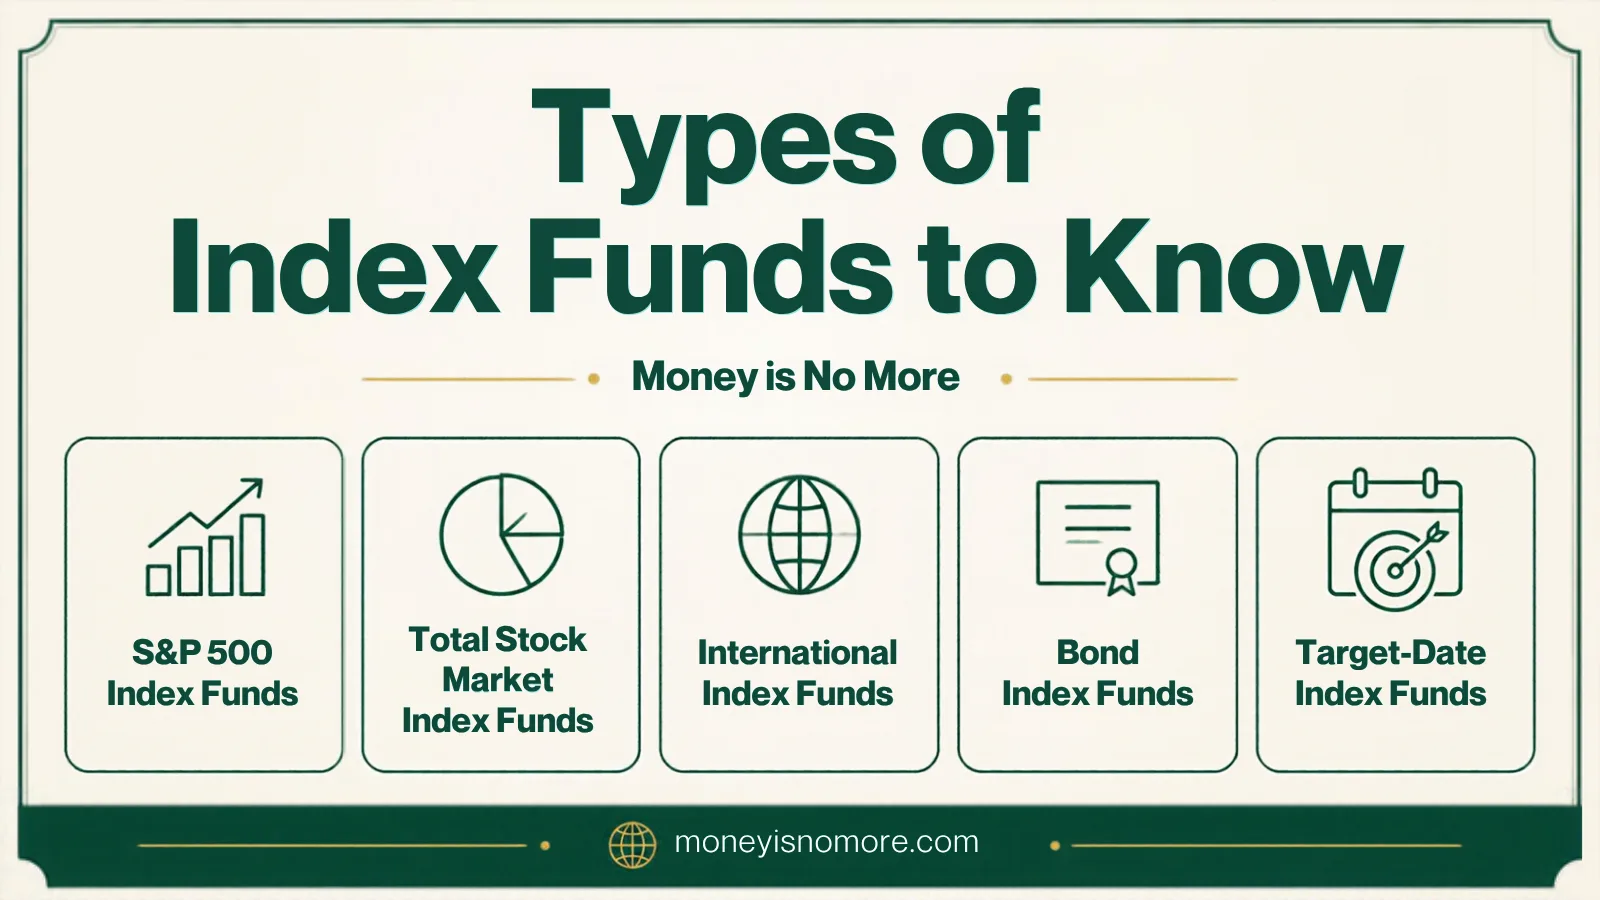
S&P 500 index funds
These track the 500 or so largest U.S. companies. They’re one of the most popular choices and a common core holding.
Total stock market index funds
These cover nearly the entire U.S. stock market, including small and mid-sized companies. They offer slightly broader diversification than an S&P 500 fund.
International index funds
These invest in companies outside the U.S. Adding international exposure spreads your risk across different economies.
Bond index funds
Bonds tend to be less volatile than stocks. Bond index funds can help smooth out your portfolio’s ups and downs, especially as you get closer to needing the money.
Target-date index funds
These hold a mix of stock and bond index funds that gradually becomes more conservative as a chosen year approaches. They’re a simple all-in-one choice for retirement savers.
How to Buy Your First Index Fund
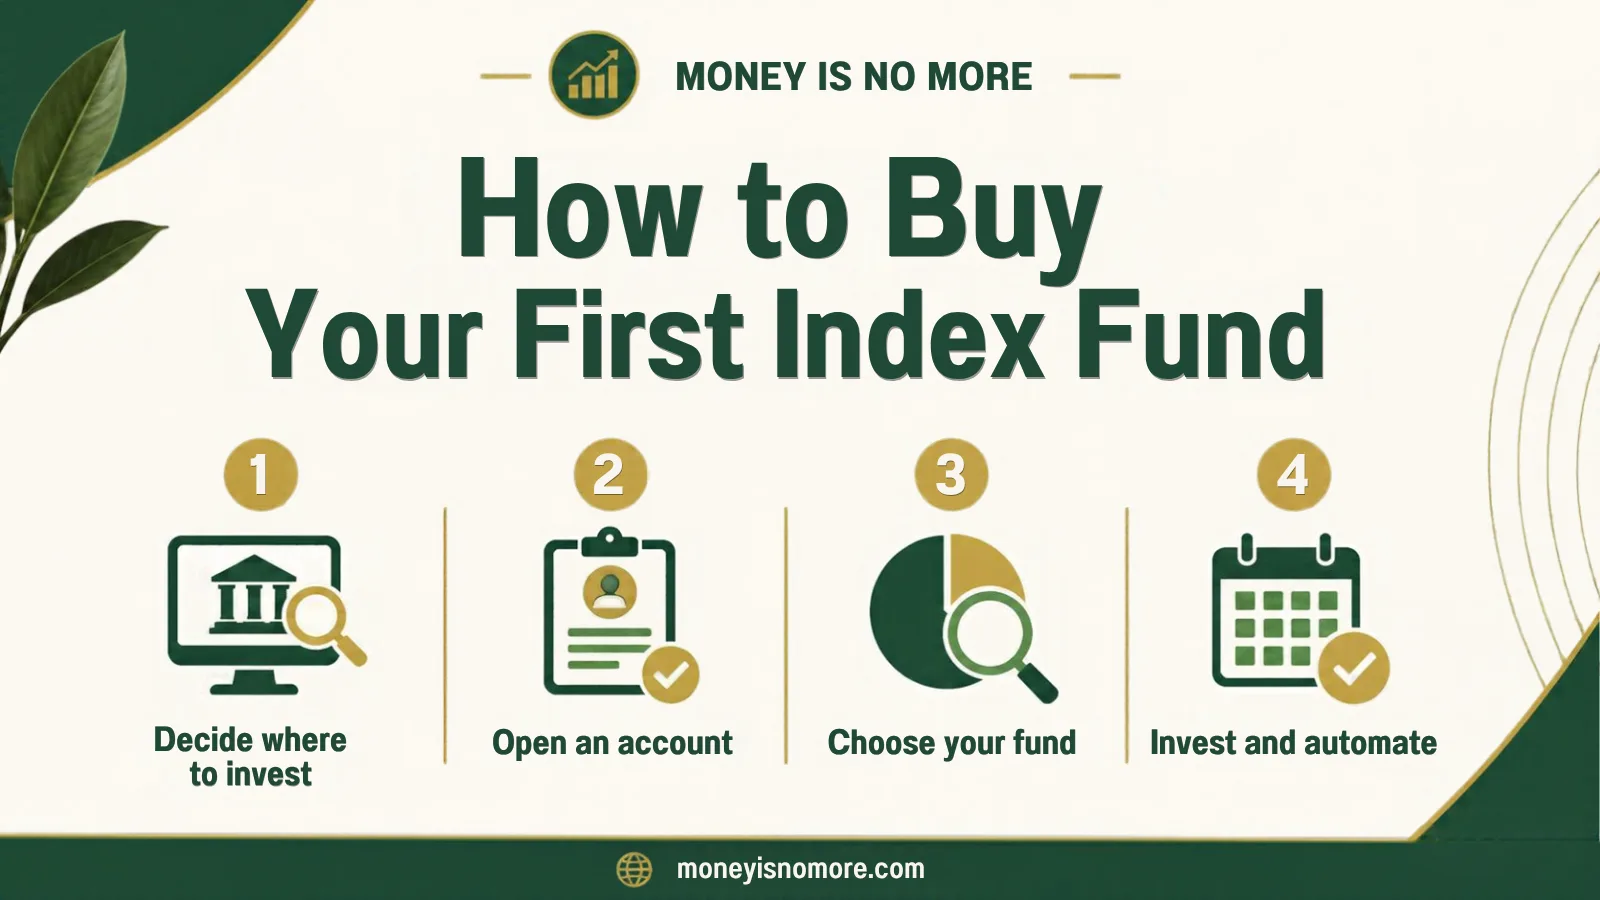
Step 1: Decide where to invest
You can buy index funds in a workplace 401(k), an IRA, or a regular brokerage account. If you’re not sure which account to use, our guide on how to start investing with little money walks through each option.
Step 2: Open an account
Choose a reputable brokerage with no account minimums, $0 commissions on ETF trades, and access to low-cost index funds. Opening an account usually takes about 15 minutes online.
Step 3: Choose your fund
Start simple. The best index funds for beginners are usually broad and low-cost. Many people pick a single total market or S&P 500 fund, or a target-date fund. When comparing funds that track the same index, look at:
- Expense ratio: lower is better.
- Tracking error: how closely the fund matches its index.
- Fund size: larger funds are generally more established.
Step 4: Invest and automate
Decide how much to invest, then set up automatic contributions. Investing a fixed amount on a regular schedule, called dollar-cost averaging, keeps you consistent without trying to time the market.
If you need help freeing up money each month, try the 50/30/20 rule or zero-based budgeting.
Risks of Index Funds
Index funds are popular, but they aren’t risk-free:
- Market risk. If the whole market falls, your index fund falls too. There’s no manager trying to avoid the drop.
- No downside protection. Index funds can’t move to cash during a crash.
- Not all index funds are cheap. Some charge much higher fees than others tracking the same index. Always check the expense ratio.
The best protection is time. Money you’ll need within a few years belongs in savings, not stocks. For longer-term goals, staying invested through downturns has historically been rewarded.
Index Funds and Passive Income
Many index funds pay dividends, which you can take as cash or reinvest automatically. Over time, reinvested dividends can become a meaningful part of your returns. For more ways to build income outside your paycheck, read our guide to passive income ideas for beginners.
Frequently Asked Questions
Are index funds good for beginners?
Yes. Index funds for beginners are a popular starting point because they offer instant diversification, low fees, and a simple, hands-off approach to long-term investing.
How much money do I need to start investing in index funds?
Many brokerages have no minimum for ETFs, and fractional shares let you start with just a few dollars. Some index mutual funds do require a minimum investment.
Can you lose money in an index fund?
Yes. Index funds rise and fall with the market they track. Over short periods they can lose value, which is why they’re best for long-term goals.
What is the difference between an index fund and an ETF?
An index fund is defined by its strategy of tracking an index. An ETF is a structure that trades like a stock. Many ETFs are index funds, and many index funds are offered as mutual funds.
How many index funds should I own?
Many beginners do well with just one to three funds, such as a total U.S. stock fund, an international fund, and a bond fund, or a single target-date fund.
The Bottom Line on Index Funds for Beginners
Index funds for beginners offer a rare combination: low costs, broad diversification, and a strategy that has outperformed most professional managers over time. Open an account, pick one or two broad funds, automate your contributions, and let time do the heavy lifting.
This article is for educational purposes only and is not personalized investment advice.
The most important step is the first one. Pick one broad, low-cost fund, set up an automatic contribution, and let time do the work.

Leave a comment