
A car repair, a trip to urgent care, or a sudden drop in work hours can turn into a financial crisis fast if you have nothing saved. Savings set aside for emergencies are what stand between a surprise bill and new debt. The good news is that you do not need a big income to start. In this guide, you will learn how to build an emergency fund step by step, how much you actually need, where to keep it, and how to grow it even on a tight budget.
Quick Answer: To build an emergency fund, start with a $500 to $1,000 starter goal, then work toward three to six months of essential expenses. Keep the money in a separate high-yield savings account, automate a transfer every payday, and add tax refunds, bonuses, and side income to reach your goal faster. That is how to build an emergency fund even on a tight budget.
Table of Contents
What Is an Emergency Fund?
An emergency fund is money set aside only for unexpected, necessary expenses, such as a job loss, medical bills, urgent car or home repairs, or a sudden trip to care for family. It is not for vacations, holiday gifts, or planned purchases.
Planned costs like car registration or holidays belong in sinking funds instead. Keeping the two separate protects your emergency money for real emergencies.
Why an Emergency Fund Matters
Many households are one surprise away from borrowing. According to the Federal Reserve’s Economic Well-Being of U.S. Households in 2025 report, 63% of adults said they would cover a $400 emergency expense using cash, savings, or a credit card paid off in full. Only 55% said they had three months of expenses saved in an emergency or rainy day fund.
Without savings, emergencies often end up on high-interest credit cards or payday loans, which makes the next month even harder. Learning how to build an emergency fund breaks that cycle.
How Much Emergency Fund Should You Have?
The common guideline is three to six months of essential expenses. Essential expenses are the costs you must pay to keep living: rent or mortgage, utilities, groceries, transportation, insurance, and minimum debt payments.
| Monthly Essential Expenses | Starter Fund | 3 Months | 6 Months |
|---|---|---|---|
| $2,000 | $1,000 | $6,000 | $12,000 |
| $2,500 | $1,000 | $7,500 | $15,000 |
| $3,000 | $1,000 | $9,000 | $18,000 |
| $4,000 | $1,000 | $12,000 | $24,000 |
Aim closer to six months, or more, if you are self-employed, have irregular income, support a family on one income, or work in an industry with frequent layoffs. Three months may be enough if you have a stable job and a two-income household. As the Consumer Financial Protection Bureau notes, the right amount depends on your situation, and even a small amount provides some security.
How to Build an Emergency Fund in 8 Steps
1. Set a Starter Goal of $500 to $1,000
Six months of expenses can feel overwhelming. Start with a smaller first goal that covers common surprises like a car repair or a medical copay. Hitting this first milestone builds momentum.
2. Calculate Your Full Target
Add up your essential monthly expenses and multiply by three to six. This becomes your long-term goal. Write it down so you always know what you are working toward.
3. Open a Separate Savings Account
Keep this money out of your checking account so it is not accidentally spent. A separate high-yield savings account makes the money easy to reach in a real emergency but out of sight day to day.
4. Automate Your Savings
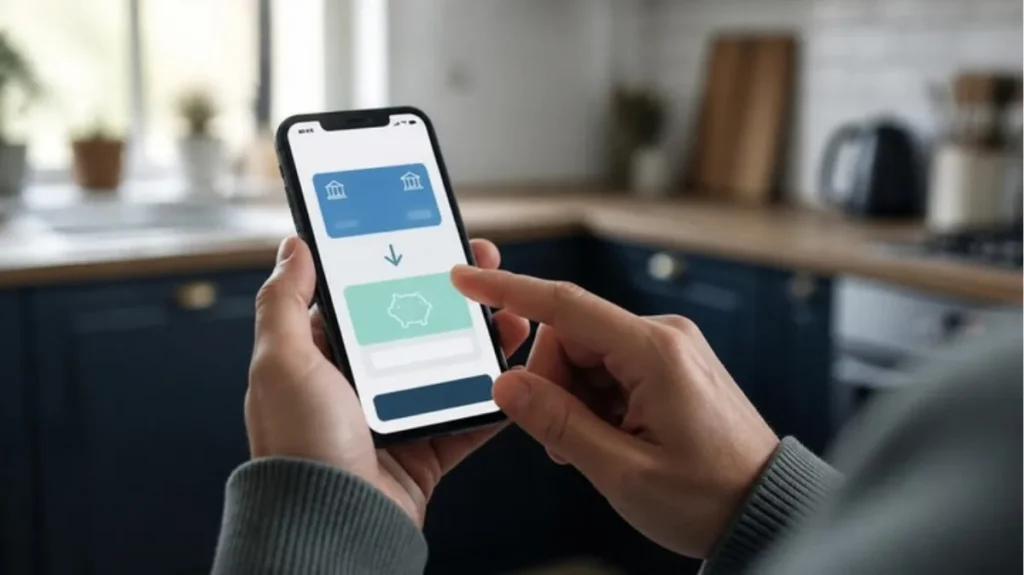
Automation is the easiest way to learn how to build an emergency fund without relying on willpower. Schedule a transfer to savings every payday, even if it is only $20 or $50. If you are paid every two weeks, two months each year have a third paycheck that you can send straight to your fund.
5. Make Room in Your Budget
Treat your emergency fund like a bill. Methods like zero-based budgeting or the 50/30/20 rule help you find money to save each month. Cancel unused subscriptions and trim your biggest bills to free up more.
6. Save Every Windfall
Tax refunds, work bonuses, cash gifts, and money from selling things you no longer need can give your fund a big boost. Saving even half of each windfall speeds up your progress.
7. Add Extra Income
A small side income can dramatically shorten your timeline. Our list of side hustles you can start this weekend has ideas that need little or no experience. Send every extra dollar to savings until you reach your goal.
8. Refill It After You Use It
This money is meant to be used. When you take money out, pause other extra goals and rebuild it as quickly as you can.
How Long Does It Take to Build an Emergency Fund?
Your timeline depends on how much you can save each month. Here is how long it takes to reach common goals:
| Monthly Savings | $1,000 Starter Fund | $7,500 (3 months at $2,500) |
|---|---|---|
| $100 | 10 months | 75 months |
| $250 | 4 months | 30 months |
| $500 | 2 months | 15 months |
| $750 | Under 2 months | 10 months |
If the timeline feels long, remember that windfalls and extra income can cut it down a lot. Interest from a high-yield account also helps a little along the way.
Where to Keep Your Emergency Fund
This money should be safe, easy to reach, and separate from everyday spending. Good options include:
- High-yield savings account: Earns more interest than a typical savings account while keeping your money available. Choose an FDIC-insured bank or NCUA-insured credit union.
- Money market account: Similar to a savings account, sometimes with check-writing features.
Avoid keeping it in the stock market, because prices can drop right when you need the money. Also avoid locking it in long-term CDs with early withdrawal penalties.
What Counts as an Emergency?
Before you withdraw, ask yourself three questions: Is it unexpected? Is it necessary? Is it urgent? A job loss, a medical bill, or a broken furnace in winter qualify. A sale, a concert, or a new phone upgrade do not.
Frequently Asked Questions
How much should I have in my emergency fund?
Most experts suggest three to six months of essential expenses. Start with a smaller goal of $500 to $1,000, then build toward the full amount over time.
What is the fastest way to build an emergency fund?
The fastest way to build an emergency fund is to combine automatic savings with extra income and windfalls. Cutting your largest expenses, even temporarily, can also speed things up.
Where is the best place to keep an emergency fund?
A high-yield savings account at an FDIC-insured bank or NCUA-insured credit union is usually the best place, because it keeps your money safe, easy to access, and earning interest.
Should I pay off debt or build an emergency fund first?
Many people build a small starter fund of $500 to $1,000 first, then focus on high-interest debt, and then finish building a full emergency fund. The starter fund keeps new emergencies from adding more debt.
Final Thoughts on How to Build an Emergency Fund
Learning how to build an emergency fund is one of the most important steps toward financial security. Start with a small goal, keep the money in a separate high-yield account, automate your savings, and add windfalls and extra income whenever you can. Every dollar you save is one less dollar you will need to borrow when life surprises you. For more ways to free up money, check out our saving money tips.

Leave a comment