
“How much should I have saved by now?” is one of the most common money questions, and one of the most stressful. Social media is full of people claiming six-figure savings at 25, which makes almost everyone feel behind.
The truth is more reassuring. Most Americans have far less in the bank than those posts suggest, and the right amount for you depends on your income, your expenses, and your goals.
This guide answers the question “how much should I have in savings by age?” with what people actually have saved at each age, the most widely used benchmarks for where you should be, and how to catch up if you’re behind.
Table of Contents
Savings vs. Retirement Savings: Know the Difference
Before looking at numbers, it helps to separate two kinds of savings:
- Cash savings is money in checking, savings, or money market accounts. It covers emergencies and short-term goals.
- Retirement savings is money invested in accounts like a 401(k) or IRA for the long run.
Both matter, but they have different targets. Your cash savings goal is based on your monthly expenses. Your retirement goal is based on your income. We’ll cover both.
How Much Do Americans Actually Have Saved by Age?
The best data comes from the Federal Reserve’s Survey of Consumer Finances, which tracks household finances every three years. The table below shows median and average balances in “transaction accounts” (checking, savings, money market, and similar accounts) from the most recent survey, conducted in 2022.
| Age of household head | Median balance | Average balance |
|---|---|---|
| Under 35 | $5,400 | $20,540 |
| 35–44 | $7,500 | $41,540 |
| 45–54 | $8,700 | $71,130 |
| 55–64 | $8,000 | $72,520 |
| 65–74 | $13,400 | $100,250 |
| 75 and older | $10,000 | $82,800 |
The overall median across all households was $8,000.
Why the median matters more than the average
The average is pulled up by a small number of very wealthy households. The median is the middle point: half of households have more, half have less. That makes it a far better picture of what a typical family actually has.
So if you’re 30 and have $5,000 in savings, you’re roughly in line with the typical household your age, even though the average looks four times higher.
How Much Cash Savings Should You Have?
The most common rule for cash savings is to hold three to six months of essential expenses in an emergency fund. Essential expenses include rent or mortgage, utilities, groceries, insurance, transportation, and minimum debt payments.
For example, if your essentials cost $3,000 a month:
- 3 months = $9,000
- 6 months = $18,000
Lean toward the higher end if you’re self-employed, have irregular income, are the only earner in your household, or have dependents. Lean toward the lower end if you have a very stable job and a dual-income household.
Many people aren’t there yet. According to the Federal Reserve’s Economic Well-Being of U.S. Households in 2025 report, 55% of adults said they had emergency savings to cover three months of expenses. If you’re in the other 45%, you have plenty of company, and a clear goal to work toward.
How Much Retirement Savings Should You Have by Age?
For retirement, the most widely cited benchmark comes from Fidelity. It suggests saving a multiple of your annual salary by each age:
| Age | Target retirement savings |
|---|---|
| 30 | 1x your salary |
| 40 | 3x your salary |
| 50 | 6x your salary |
| 60 | 8x your salary |
| 67 | 10x your salary |
So if you earn $60,000 a year, the guideline suggests about $60,000 saved for retirement by 30 and $180,000 by 40.
These targets assume you start saving 15% of your income at age 25 and invest a good portion in stocks. If you started later or earn less, the numbers can feel out of reach. Treat them as a direction, not a pass/fail test.
Savings Goals by Age: A Practical Breakdown
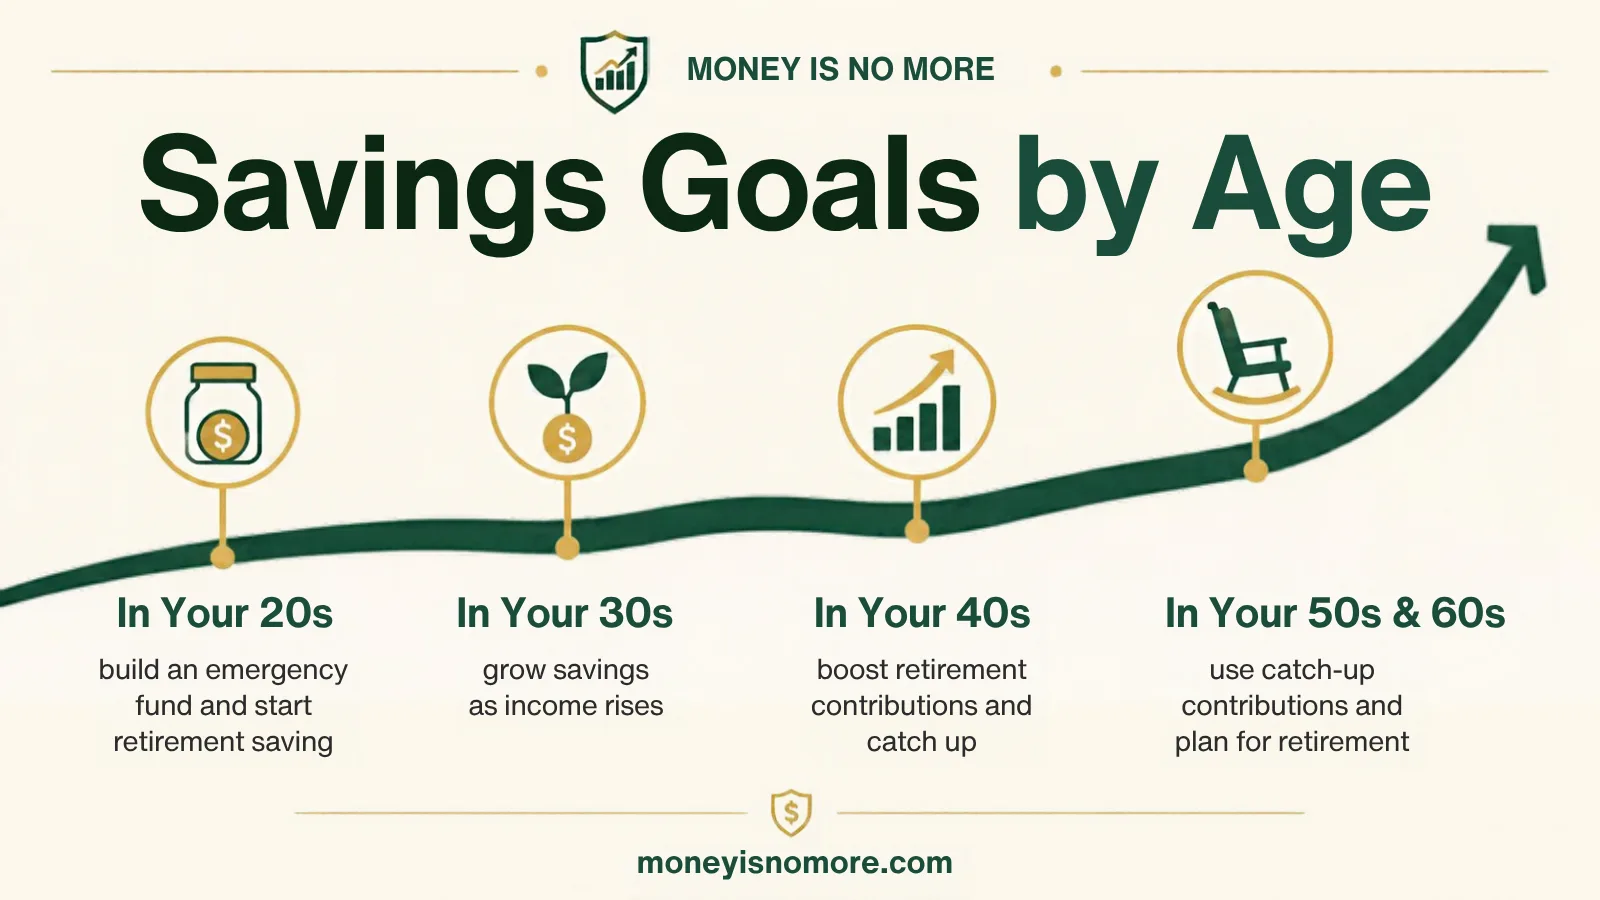
In your 20s
Focus on building habits rather than hitting big numbers. Good goals for this decade:
- Build a starter emergency fund of $1,000 to $2,000, then grow it toward three months of expenses.
- Contribute enough to your 401(k) to get any employer match.
- Pay off high-interest debt.
If you’re still in school, a few side hustles that fit a class schedule can help you start saving early.
In your 30s
Your income usually rises in your 30s, but so do expenses like housing and children. Aim to:
- Reach a full three-to-six-month emergency fund.
- Work toward 1x to 3x your salary in retirement savings.
- Save for big goals like a home in separate accounts.
In your 40s
This is often your peak earning decade. Use it to:
- Raise retirement contributions toward 15% or more of your income.
- Aim for 3x to 6x your salary in retirement savings.
- Avoid letting lifestyle creep eat every raise.
In your 50s and 60s
Now the focus shifts to closing gaps and preparing for retirement:
- Take advantage of catch-up contributions. For 2026, the IRS lets people 50 and older contribute an extra $8,000 to a 401(k) and an extra $1,100 to an IRA.
- Pay down debt before retirement.
- Consider keeping a larger cash cushion as you get closer to leaving work.
What If You’re Behind?
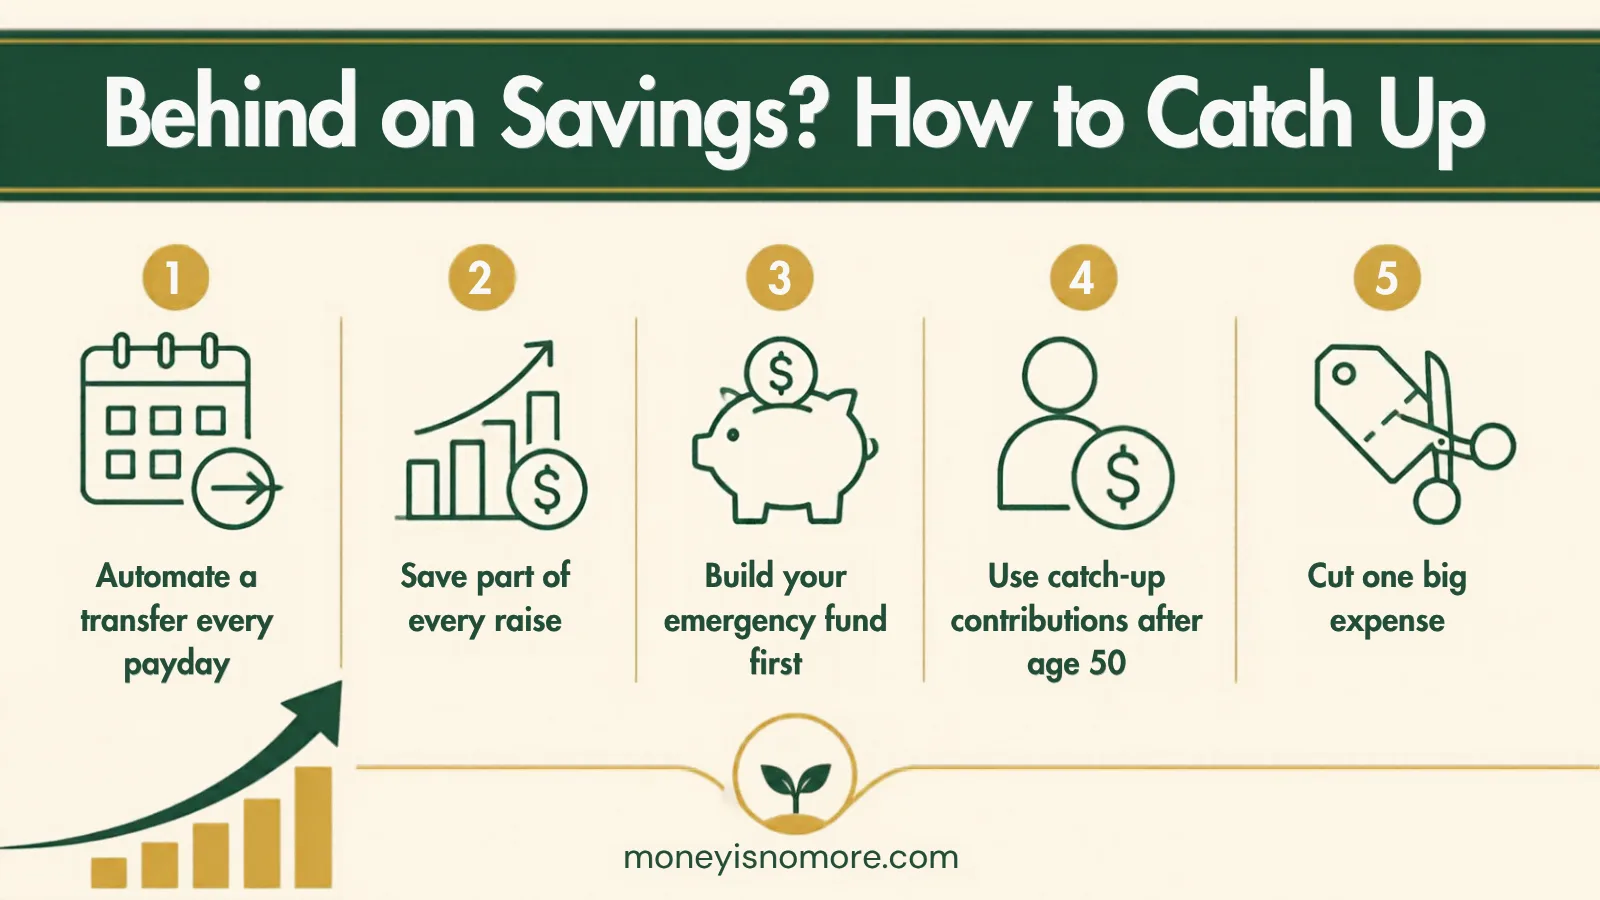
Most people are behind at least one benchmark, so don’t panic. Here’s how to catch up:
- Start with your budget. You can’t save more without knowing where your money goes. The 50/30/20 rule is a simple place to start.
- Automate your savings. Set up transfers on payday so saving happens before spending.
- Increase your savings rate gradually. Raise it by 1% every few months or every time you get a raise.
- Use a structured plan. Our guide on how to save $10K in a year breaks a big goal into weekly steps.
- Grow your income. Extra earnings make every other step easier. Even passive income ideas can add up over time.
If you’re stuck living paycheck to paycheck, start with these steps to break the cycle before worrying about age benchmarks.
If you keep asking yourself how much should I have in savings by age, remember that benchmarks are a guide, not a grade. They are built on averages, and your situation is your own. A person who paid off student loans in their 30s or took time off to raise kids will look “behind” on paper, even if they are making smart choices.
What matters most is the direction you are heading. A few habits make a big difference over time: automate a transfer to savings on every payday, raise your savings rate a little each time you get a raise, and keep your emergency fund separate from your spending account so it is not easy to dip into.
The Bottom Line
There’s no single number you should have saved by a certain age. A good target is three to six months of expenses in cash, plus retirement savings that grow toward roughly 10x your salary by retirement age.
If you’re behind, the best time to start is now. Small, consistent steps matter far more than how you compare to someone else.
So, how much should I have in savings by age? Enough to cover emergencies today, plus steady progress toward retirement. Start where you are, save consistently, and let time do the heavy lifting.
Frequently Asked Questions
How much should a 30-year-old have in savings?
A common goal is three to six months of expenses in an emergency fund, plus about 1x your annual salary in retirement savings. The typical household under 35 has a median of $5,400 in transaction accounts, so many people are still working toward these targets.
How much savings is considered good?
Having three to six months of essential expenses saved is a solid cash target. For retirement, being on track with benchmarks like 3x your salary by 40 is considered good progress.
What is the median savings in the U.S.?
According to the Federal Reserve’s 2022 Survey of Consumer Finances, the median transaction account balance for all U.S. households was $8,000.
Is it too late to start saving at 40 or 50?
No. Higher income in your 40s and 50s, plus catch-up contributions after 50, can help you make up a lot of ground. Starting now is always better than waiting.
Should I save or invest?
Build an emergency fund in cash first. After that, invest for long-term goals like retirement, since cash savings alone usually don’t keep pace with inflation over decades.

Leave a comment