
Have you ever had your budget wrecked by a bill you knew was coming, like car registration, holiday gifts, or a yearly insurance payment? Those expenses are not true emergencies, but they still feel like one when you have not planned for them. That is exactly what sinking funds are designed to fix. In this guide, you will learn what they are, how they work, 15 common sinking funds examples, and how to set yours up in a few simple steps.
Quick Answer: Sinking funds are small amounts of money you save each month for a specific planned expense, like holidays, car repairs, insurance, or a vacation. To start, list your irregular expenses, divide each yearly cost by 12, and automatically save that amount every month so the money is ready when the bill arrives.
Table of Contents
What Are Sinking Funds?
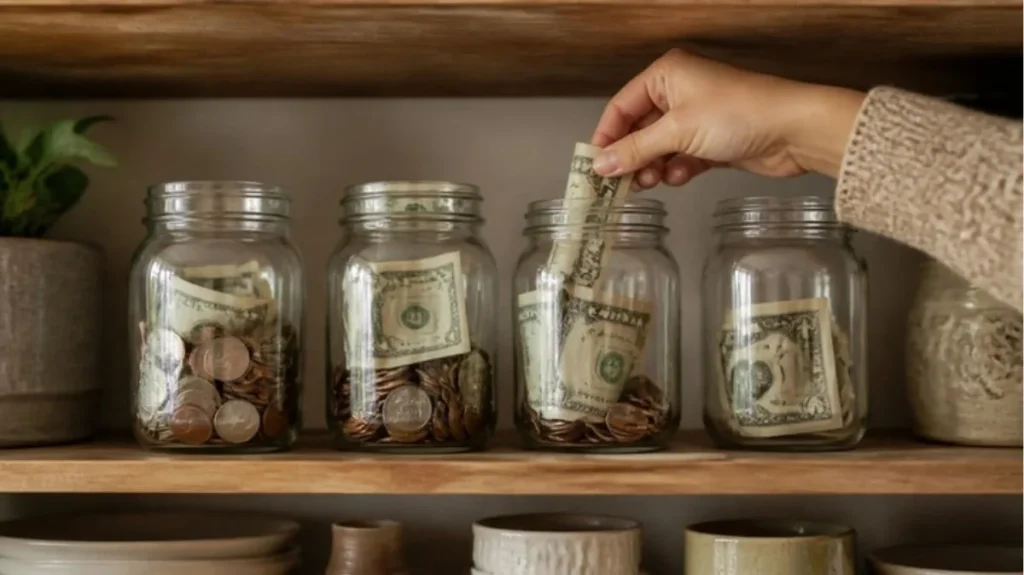
A sinking fund is money you set aside a little at a time for a specific, planned expense. Instead of paying for a large cost all at once, you divide it into small monthly amounts and save toward it ahead of time. When the bill arrives, the money is already waiting.
For example, if you know your car insurance costs $900 every year, you would save $75 a month in a car insurance fund. When the bill is due, you pay it in full without touching your regular budget or reaching for a credit card.
In personal finance, this is simply a budgeting tool. The term also has a separate meaning in corporate finance, where a sinking fund is money a company sets aside to repay bonds or other debt over time. This guide focuses on the personal budgeting version.
How Do Sinking Funds Work?
Sinking funds follow a simple formula:
Total cost ÷ number of months until you need it = monthly savings amount
If you want $1,200 for holiday gifts in 10 months, you need to save $120 a month. If you want $600 for car repairs over the next 12 months, you save $50 a month. Once the expense is paid, you start the cycle again for next year.
Sinking Fund vs. Emergency Fund
These two are often confused, but they serve different purposes:
| Sinking Fund | Emergency Fund | |
|---|---|---|
| Purpose | Planned, expected expenses | Unexpected emergencies |
| Examples | Holidays, car registration, vacations | Job loss, medical emergency, urgent repairs |
| Timing | You know roughly when you will need it | You do not know when you will need it |
| Goal | Spend it on schedule, then refill | Keep it untouched for true emergencies |
You need both. Planned-expense savings protect your emergency fund, because planned costs no longer eat into money meant for real emergencies.
Why Sinking Funds Are Worth It
- No more budget surprises: Irregular bills stop throwing off your month.
- Less debt: You pay cash instead of using credit cards for predictable costs.
- Less stress: You know the money is there before the bill arrives.
- Guilt-free spending: Money saved for a vacation or gifts is already planned, so you can enjoy it.
15 Sinking Funds Examples
Here are common sinking funds examples with sample yearly costs. Your real numbers will be different, so use your own bills and past spending to set your targets.
| Sinking Fund | Example Yearly Cost | Monthly Savings |
|---|---|---|
| Car maintenance and repairs | $600 | $50 |
| Car insurance (paid yearly or every 6 months) | $900 | $75 |
| Car registration and inspection | $240 | $20 |
| Holidays and gifts | $1,200 | $100 |
| Birthdays and celebrations | $300 | $25 |
| Vacation or travel | $1,800 | $150 |
| Home maintenance and repairs | $1,200 | $100 |
| Medical and dental costs | $600 | $50 |
| Pet care and vet visits | $600 | $50 |
| Back-to-school supplies | $480 | $40 |
| Clothing | $360 | $30 |
| Annual subscriptions and memberships | $240 | $20 |
| New phone or electronics | $600 | $50 |
| Home furniture and appliances | $600 | $50 |
| Next car down payment | $2,400 | $200 |
You do not need all 15. Most people start with three to five funds for the expenses that hurt their budget most often.
How to Start Sinking Funds in 5 Steps
1. List Your Irregular Expenses
Look through the last 12 months of bank and card statements. Write down every expense that does not happen monthly, such as insurance premiums, gifts, car repairs, and yearly subscriptions.
2. Estimate the Yearly Cost of Each
Use last year’s actual spending as your guide. If a cost varies, round up to give yourself a buffer.
3. Calculate Your Monthly Amount
Divide each yearly cost by the number of months until you need it. Add up all of your funds to see the total monthly amount you need to save.
4. Add Sinking Funds to Your Budget
Treat sinking funds like a regular bill. They fit naturally into zero-based budgeting, where every dollar gets a job, and into the savings portion of the 50/30/20 rule. If your total feels too high, start with your most important funds and add the rest later.
5. Automate Your Transfers
Set up automatic transfers on payday so your savings grow without effort. If you are paid every two weeks, remember that some months have three paychecks, which is a great time to give your savings a boost.
Where to Keep Your Sinking Funds
You have a few good options:
- A high-yield savings account: Your money earns interest while it waits. As of late September 2026, many high-yield accounts pay around 4% APY, compared with a national average of about 0.64%. Some banks let you create multiple savings “buckets” in one account, which is perfect for sinking funds.
- Separate savings accounts: One account per fund keeps everything clearly separated.
- A spreadsheet with one account: Keep all the money together and track each fund’s balance in a simple spreadsheet.
- Cash envelopes: If you like physical cash, the cash envelope method works well for smaller goals like gifts or clothing.
Common Sinking Fund Mistakes to Avoid
- Starting too many at once: Begin with a few important funds so you do not get overwhelmed.
- Underestimating costs: Round up and check real past spending.
- Borrowing between funds: Moving money from your vacation fund to cover dining out defeats the purpose.
- Forgetting to refill: After you spend a fund, restart it for next year right away.
Frequently Asked Questions
What is a sinking fund in simple terms?
A sinking fund is money you save a little at a time for a specific planned expense, like holidays, car repairs, or a vacation, so you can pay for it in full when it arrives.
How many sinking funds should I have?
Most people start with three to five sinking funds for their biggest irregular expenses, then add more as their budget allows.
Are sinking funds the same as an emergency fund?
No. Sinking funds are for planned expenses you know are coming. An emergency fund is for unexpected events like a job loss or a medical emergency.
Where should I keep my sinking funds?
A high-yield savings account is a popular choice because your money earns interest. Some banks let you create separate savings buckets for each fund.
Final Thoughts on Sinking Funds
Sinking funds turn big, stressful bills into small, manageable monthly amounts. Start by listing your irregular expenses, pick three to five goals, calculate what you need each month, and automate your savings. In a few months, the bills that used to surprise you will simply be paid, and your budget will finally feel under control. For more ways to free up money to save, check out our saving money tips.

Leave a comment