
Payday comes, the bills go out, and a few days later your account is almost empty again. If that cycle sounds familiar, you are not alone, and you are not bad with money. Breaking the cycle is less about earning a fortune and more about building a few simple systems. In this guide, you will learn how to stop living paycheck to paycheck with 10 practical steps you can start this week, even on a tight income.
Quick Answer: To stop living paycheck to paycheck, track your spending for 30 days, build a simple budget, save a starter emergency fund of $500 to $1,000, pay yourself first with automatic transfers, cut your biggest bills, stop adding new debt, and find ways to earn more. Small, steady steps are the key to how to stop living paycheck to paycheck for good.
Table of Contents
What Does Living Paycheck to Paycheck Mean?
Living paycheck to paycheck means that almost all of your income is spent on bills and daily costs before your next payday arrives. There is little or nothing left over to save, so any surprise expense, like a car repair or a medical bill, can push you into debt.
It is not only a low-income problem. People with good salaries can live paycheck to paycheck too if their spending rises every time their income does.
The numbers show how common this is. According to the Federal Reserve’s Economic Well-Being of U.S. Households in 2025 report, 63% of adults said they would cover a $400 emergency expense using cash, savings, or a credit card paid off in full. That means more than a third would need to borrow, sell something, or could not pay at all. Only 55% said they had three months of expenses set aside in an emergency fund.
Signs You Are Living Paycheck to Paycheck
- Your checking account is close to zero right before payday.
- You have less than one month of expenses saved.
- You use a credit card or buy now, pay later for everyday purchases.
- A single unexpected bill would force you to borrow money.
- You do not know exactly where your money went last month.
If two or more of these sound like you, the steps below will help.
How to Stop Living Paycheck to Paycheck: 10 Steps That Work
1. Track Every Dollar for 30 Days
You cannot fix what you cannot see. For one month, write down every purchase, or use your bank app to review transactions each week. Group spending into simple categories like housing, food, transportation, subscriptions, and fun. Most people find at least one category where money quietly disappears.
2. Build a Simple Budget Around Your Paycheck
Once you know where your money goes, give it a plan before payday arrives. Learning how to budget your paycheck is the foundation of learning how to stop living paycheck to paycheck. Two beginner-friendly methods are zero-based budgeting, where every dollar gets a job, and the 50/30/20 rule, which splits income into needs, wants, and savings. Pick one and stick with it for three months.
3. Start a Starter Emergency Fund
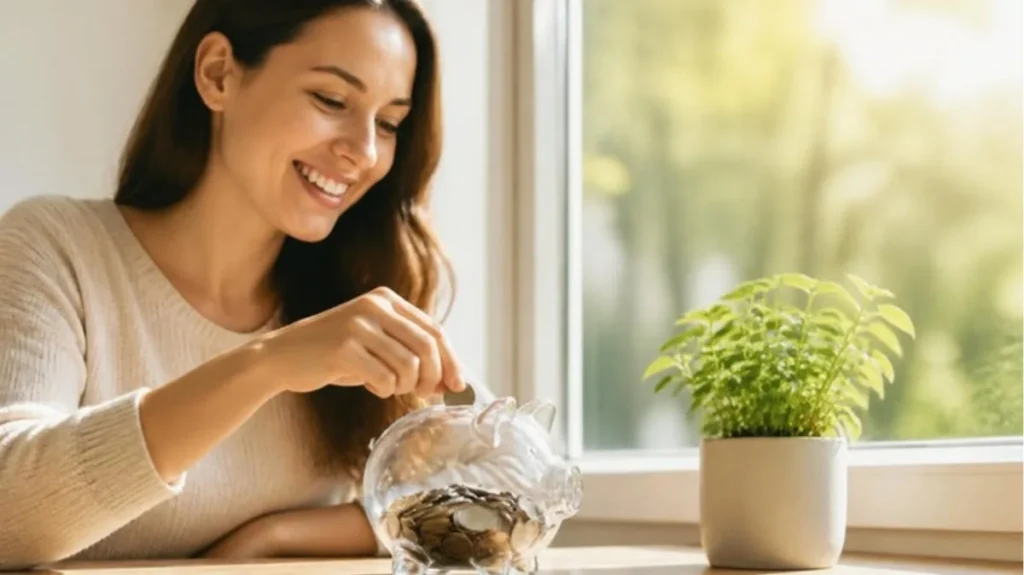
An emergency fund is what breaks the cycle. Without one, every surprise becomes new debt. Start with a small goal, such as $500 or $1,000, and keep it in a separate high-yield savings account so you are not tempted to spend it. Once you reach that goal, build toward three to six months of essential expenses.
4. Pay Yourself First
Do not wait to see what is left at the end of the month, because there is rarely anything left. Set up an automatic transfer to savings on payday, even if it is only $10 or $20. When saving happens automatically, you adjust your spending to what remains in your checking account.
5. Cut Your Biggest Expenses First
Canceling one streaming service helps, but the fastest progress comes from your largest bills. Call your car insurance and phone providers and ask for a lower rate, shop around at renewal time, and consider a cheaper housing or transportation option if these costs take up too much of your income. For more ideas, see our list of saving money tips.
6. Review Subscriptions and Recurring Charges
Go through the last three months of bank and card statements and highlight every recurring charge. Cancel anything you have not used in the last 30 days. Small monthly charges are easy to forget, but together they can add up to hundreds of dollars a year.
7. Use Cash for Problem Categories
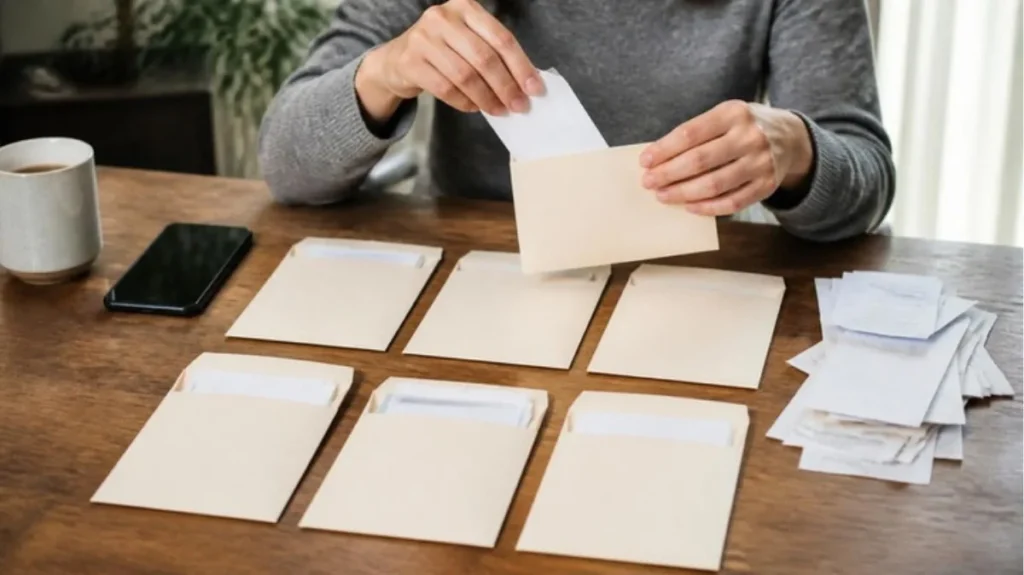
If you always overspend on groceries, eating out, or shopping, switch those categories to cash. When the cash is gone, you stop spending until the next payday. Our guide to cash envelope budgeting shows how to set this up in a simple way.
8. Stop Adding New Debt
You cannot learn how to stop living paycheck to paycheck while interest charges keep growing. Put your credit cards away while you build your emergency fund. Then pay down high-interest debt one balance at a time, starting with either the smallest balance or the highest interest rate.
9. Plan for Irregular Expenses
Car registration, holidays, birthdays, and annual subscriptions are not true emergencies, because you know they are coming. Add up these yearly costs, divide by 12, and set that amount aside each month. If you are paid biweekly, remember that some months have three paychecks. Use those extra paychecks to fund savings instead of spending them.
10. Increase Your Income
Cutting costs has a limit, but earning more does not. Ask for a raise, pick up extra shifts, or start a flexible side income. Our list of side hustles you can start this weekend has ideas that need little or no experience. Send every extra dollar straight to your emergency fund or debt until you have a real cushion.
A Simple 30-Day Plan to Break the Cycle
Knowing how to stop living paycheck to paycheck is one thing, but acting on it is what changes your life. Here is a simple plan for your first month:
- Week 1: Track every purchase and list all of your bills and due dates.
- Week 2: Build your first budget and cancel any subscriptions you do not use.
- Week 3: Open a separate savings account and set up an automatic transfer on payday.
- Week 4: Call one or two providers to lower a bill, and plan one way to earn extra money.
By the end of the month, you will have a budget, a savings habit, and a clear picture of your money. That is the real starting point for how to stop living paycheck to paycheck for good.
Common Mistakes That Keep You Stuck
- Lifestyle creep: Spending every raise instead of saving part of it.
- No buffer in checking: Running your account down to zero leads to overdraft fees.
- Budgeting once and forgetting it: A budget only works if you review it every payday.
- Trying to change everything at once: Small, steady changes last longer than drastic cuts.
Frequently Asked Questions
How do I stop living paycheck to paycheck on a low income?
Start by tracking your spending and building a simple budget. Focus on your largest bills, save even a small amount automatically each payday, and look for ways to add income, such as extra shifts or a side hustle. Small, consistent steps matter more than large amounts.
How long does it take to stop living paycheck to paycheck?
It depends on your income, expenses, and debt. Many people can build a starter emergency fund of $500 to $1,000 within a few months by cutting expenses and saving automatically. Building a full emergency fund of three to six months takes longer.
What is the first step to stop living paycheck to paycheck?
The first step is tracking where your money goes for 30 days. Once you see your real spending, you can build a budget and start saving.
How much should I save to stop living paycheck to paycheck?
Start with a goal of $500 to $1,000 as a starter emergency fund. After that, work toward three to six months of essential expenses.
Final Thoughts on How to Stop Living Paycheck to Paycheck
Learning how to stop living paycheck to paycheck does not require a huge raise or perfect discipline. It starts with knowing where your money goes, giving every dollar a plan, and saving a little from every paycheck before you spend it. Build a small emergency fund, stop adding new debt, and look for ways to grow your income. Each step makes the next one easier, and in a few months, payday can feel like progress instead of relief.

Leave a comment